Before you look
Three steps that make every later step easier
Buyers who start organized finish calmer. Do these three things before the first showing, and the offer, the financing, and the closing all move faster.
Get pre-approved before you tour
Pre-approval tells you the purchase price you can support and makes your offer credible to sellers. Your lender reviews income, assets, credit, and debts and issues a letter stating the amount and loan type you qualify for. At 2813 S Terry Ave, a list price of $725,000 means loan size matters, so know your number before you fall for the deck view.
Budget the whole monthly payment, HOA included
Lenders count HOA dues as part of your monthly housing expense. On this townhome, the $365 per month association fee covers garbage, snow removal, and lawn care, and it sits on top of principal, interest, taxes ($8,373 per year per listing information), and insurance. A realistic budget includes all of it.
Write your must-haves and your walk-aways
Decide what the townhome must have (two suites? a heated garage? lake views?) and what you can flex on. That list makes showings faster and keeps offers calm. Jennifer helps first-time buyers and relocation clients build this list on the first conversation.
Step one
How to view a townhome like an inspector's friend
A showing is your chance to gather evidence, not to fall in love. Bring this checklist to every townhome you tour, including this one.
Read the systems, not just the finishes
A 2018 build like this one is newer than much of the housing stock here, but age never replaces an inspection. At a showing, ask about the furnace, AC, water heater, roof, and major appliances, their age, and their remaining life. Jennifer's construction and electrical background means she walks you through exactly what to check.
Understand the shared structure
A townhome means party walls and neighbors past them. Notice where the bedrooms sit relative to shared walls, tour at the times of day you would actually live there if you can, and ask how the association maintains the shared structure. Accept attached living before you offer, not after.
Open the garage and read the floor
This listing's attached garage is heated, 24 by 22 feet, with an epoxy floor, floor drain, and hot and cold water. At any townhome, confirm the garage fits your vehicles, your storage, and your winter gear. In Sioux Falls, a warm garage and a warm car are real features.
Tour the neighborhood at honest times
Visit on a weekday evening and a weekend. Watch traffic at the cross street (Westlake Drive here), check how close the lake walk and retail really are, and notice who else is out. Granite countertops photograph well; the daily commute does not.
Ask for the HOA documents before you leave
The $365 fee is one number; the governing documents are the real story. Request the declaration, bylaws, and rules before you make an offer, and read the sections on rentals, pets, parking, and exterior changes, even if you think they do not apply to you.
Check the taxes and the fine print
Taxes here are about $8,373 per year per the listing information, and the figure can change with assessments, so verify the current number with the county. Square footage, HOA details, and school assignments should all be confirmed independently before you rely on them.
The Jennifer difference: before real estate, Jennifer worked in construction, electrical, and workplace safety, and with the City of Sioux Falls. She points out the condition and long-term value of a home, not just what photographs well. Ask her about any system on the tour.
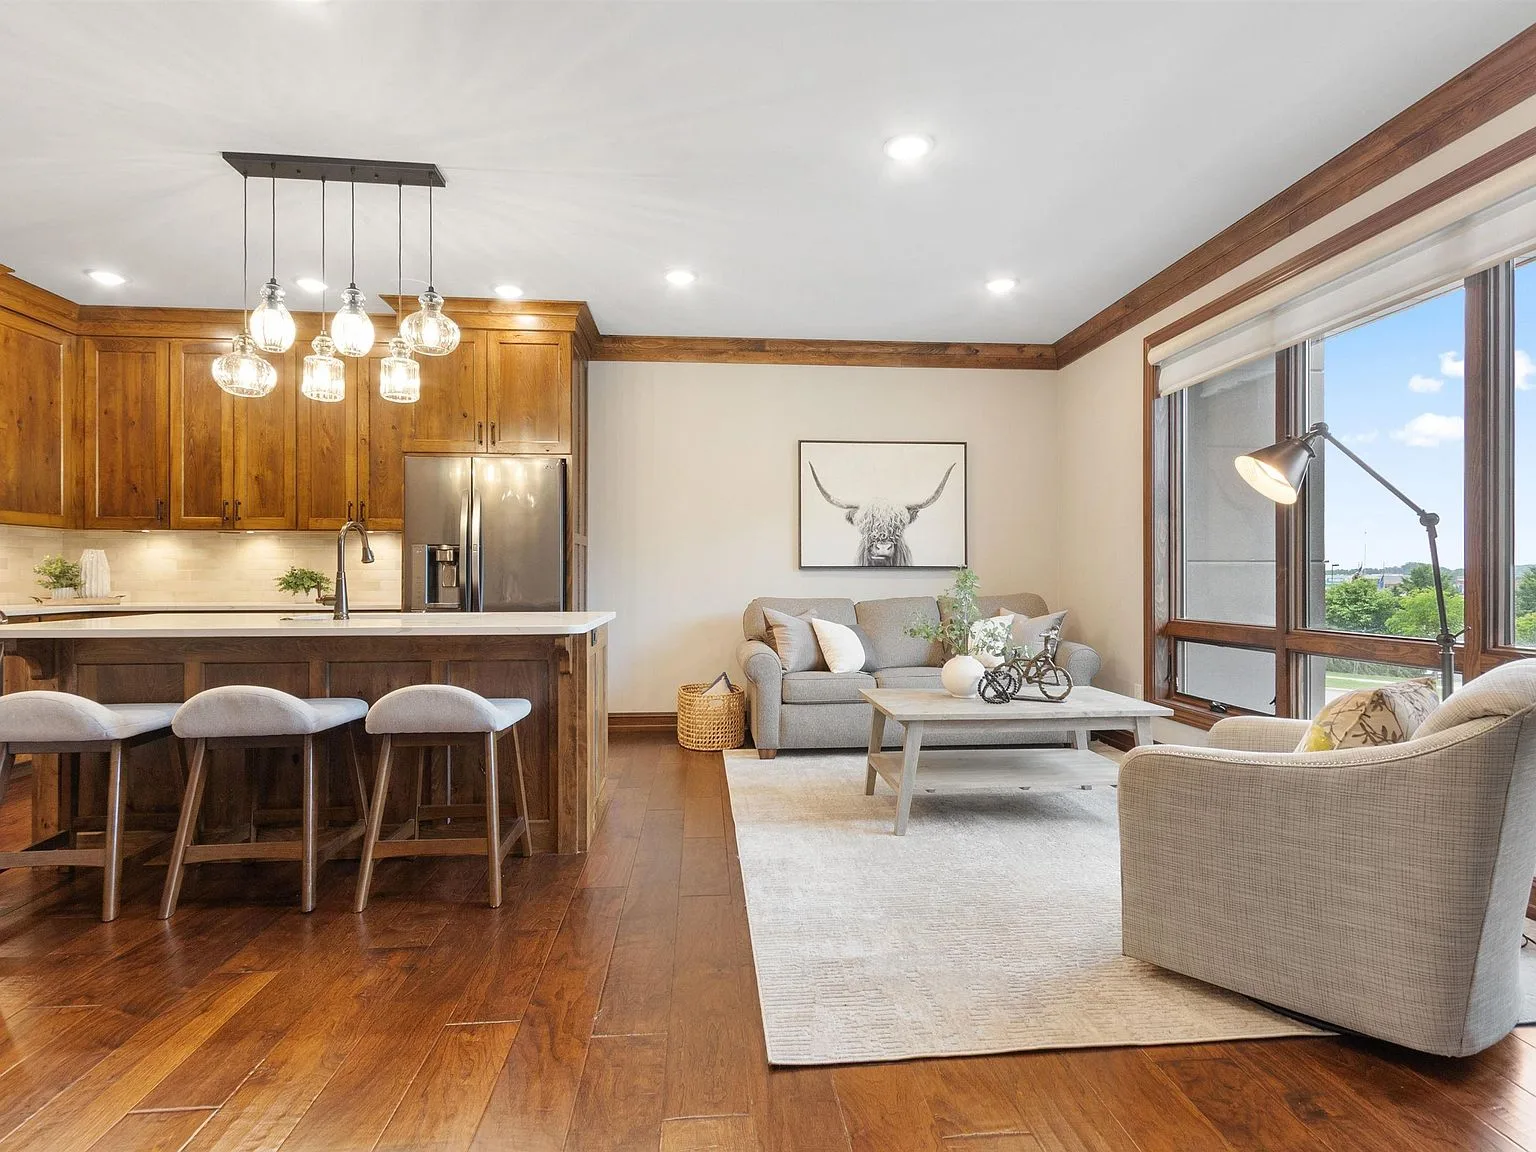
The main-level open concept at 2813 S Terry Ave: kitchen, dining, and living in one bright space.
Step two
Making an offer in South Dakota
Your offer becomes real on paper. In South Dakota, that paper is the state's standard Residential Purchase Agreement, and the shape of the offer matters as much as the price. Here is what goes into a strong, competitive one.
- Written on South Dakota's Residential Purchase Agreement, the standard contract used across the state
- Earnest money is typically 1 to 3 percent of the price, held in escrow by a closing company or title company, and credited toward your down payment at closing
- An inspection contingency, usually days to complete, lets you hire a professional inspector and negotiate repairs or cancel with your earnest money returned
- A financing contingency protects you if your loan does not come through, and an appraisal contingency covers the gap if the home appraises below the price
- Seller concessions are negotiable: at 2813 S Terry Ave, the seller pays 12 months of HOA dues with an acceptable offer, subject to the terms you agree on
Note the concession pattern at this listing: the seller offers 12 months of HOA dues with an acceptable offer, subject to agreed purchase agreement terms. Concessions like this are negotiation points, and Jennifer will show you how to use them.
Step three
Financing and closing, step by step
The road from accepted offer to closing has five checkpoints. Some overlap, all of them have deadlines, and a good lender plus a responsive agent keep them on track. Financed purchases in South Dakota typically close about 30 to 45 days after acceptance.
Pre-approval
Know your number before you tour. A lender reviews your full financial picture and issues a pre-approval letter that sellers expect to see with an offer.
Offer and acceptance
Your agent writes the offer on the South Dakota purchase agreement with price, contingencies, and dates. Once signed, the closing clock starts.
Inspection and appraisal
A professional inspection verifies the home's condition and the lender orders an appraisal to confirm the value. Issues found here become negotiation points.
Underwriting
Your lender verifies income, assets, credit, and the property details, then clears the file. Respond to document requests quickly to stay on schedule.
Closing
Financed purchases in South Dakota typically close about 30 to 45 days after acceptance; cash deals can move faster. At closing you sign the final documents, the deed transfers, and you get the keys.
What the HOA does to your financing: your lender counts the $365/mo association fee as part of your monthly housing expense, which lowers the loan amount you qualify for. Depending on how this home is legally classified, FHA and VA loans may also require the association to meet project approval rules.
The honest caveats: closing costs, the appraisal, and the timeline all depend on your specific loan, lender, and contract dates. Every number here is a general range, not a quote. Jennifer works with trusted local lenders and will connect you before you shop.
Townhome extras
Four checks that are townhome specific
A townhome adds a layer of shared ownership that single-family buyers never touch. These four checks protect you in that layer.
Read the HOA packet in full
The dues, the reserves, the rules, and the recent minutes all live in the documents. At this townhome the $365 monthly fee covers garbage, snow removal, and lawn care; what it does not cover (your interior, utilities, and taxes) matters just as much.
Know the legal classification
Whether the home is recorded as a condominium or a fee-simple townhome affects financing options, especially for FHA and VA loans. Ask the agent and your lender which category applies before you commit to a loan path.
Ask about noise and neighbors
Shared walls are the honest trade-off of attached living. Ask how the current owners experience sound, whether the association has quiet-hour rules, and what the rental policy is, because a shift in renters changes the feel of a building.
Plan insurance and maintenance
Townhome insurance can differ from single-family policies depending on what the association master policy covers. Ask your insurer about dwelling coverage, interior finish coverage, and liability, and budget for the maintenance the HOA does not handle.
Want the room-by-room version? Read the questions to ask before buying a townhome and the first-time buyer's checklist on the blog for the full checklist treatment.
Next step
Start the process with a guide, not a guess
Jennifer specializes in first-time home buyers and relocation, and she has walked buyers through every step on this page many times. Tell her where you are in the process (just looking, pre-approved, or ready to offer) and she will tell you exactly what comes next.
Tell her where you are in the process
Just looking, pre-approved, or ready to make an offer on 2813 S Terry Ave? Jennifer plans the next step with you.